Market overview and structural significance of the Ferroelectric Materials Market
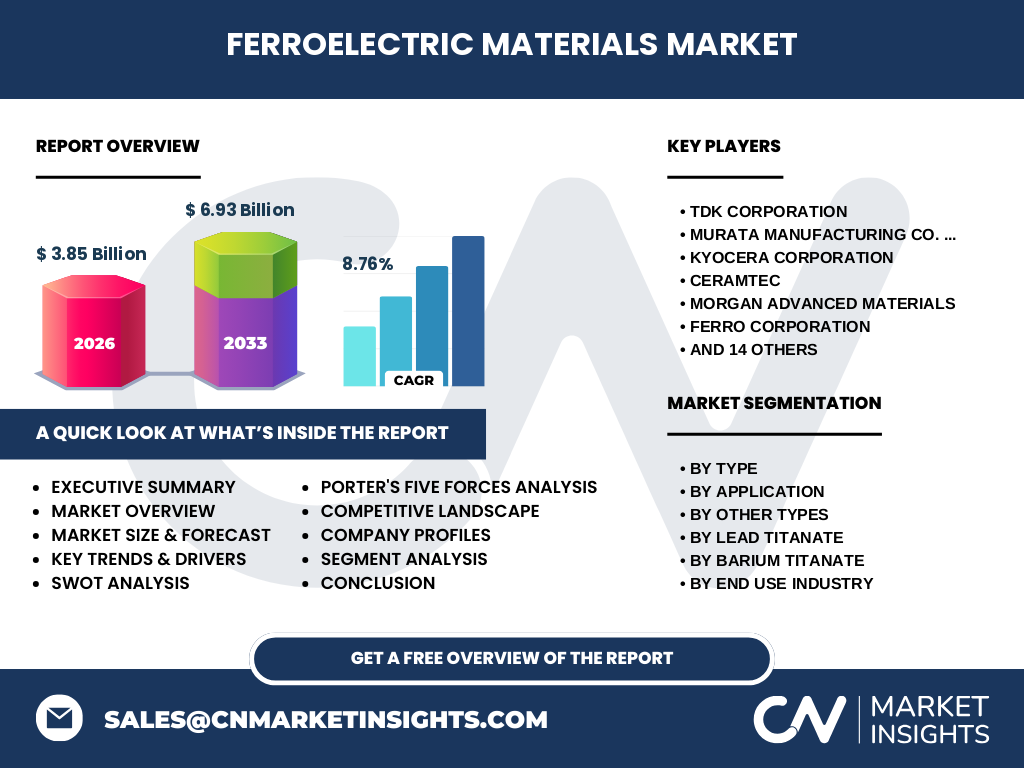
Our analysis indicates that the Ferroelectric Materials Market represents a foundational pillar for advanced electronics, valued at 3.85 Billion in 2026. This sector encompasses specialized inorganic and organic crystalline compounds exhibiting spontaneous electric polarization that can be reversed by an external electric field. These materials are critical for enabling high-density energy storage, precise actuation, and frequency tuning across diverse high-tech manufacturing ecosystems globally.
What are the primary growth drivers and market restraints shaping the Ferroelectric Materials Market industry trends?
The market is propelled by accelerating miniaturization trends in consumer electronics and expanding deployment of 5G infrastructure. However, strict environmental compliance regarding toxic constituents such as lead in traditional formulations poses significant regulatory hurdles. Lead Zirconate Titanate (PZT) restrictions under RoHS directives compel manufacturers to accelerate R&D toward viable lead-free alternatives like Sodium Potassium Niobate.
Emerging technological trends in the Ferroelectric Materials Market
The industry is witnessing a decisive pivot toward environmentally benign lead-free compositions, particularly Sodium Potassium Niobate and advanced Polyvinylidene Fluoride (PVDF) polymer films. Ferroelectric random-access memory (FeRAM) integration is gaining traction, driven by the demand for non-volatile memory solutions boasting ultra-low power consumption and high endurance rates across mission-critical aerospace and automotive applications.
How did the COVID-19 pandemic impact the Ferroelectric Materials Market recovery trajectory?
Pandemic-induced supply chain disruptions severely constrained raw material procurement, particularly for high-purity Barium Titanate precursors. Nevertheless, post-crisis recovery has been robust, underpinned by accelerated digital transformation initiatives and surging automotive electrification rates. The market rebounded rapidly as semiconductor fabrication plants resumed full-capacity operations to address acute component backlogs.
Competitive landscape and strategic dynamics in the Ferroelectric Materials Market
Market concentration is notably high, dominated by specialized chemical and ceramic innovators such as TDK Corporation, Murata Manufacturing Co. Ltd., and Kyocera Corporation. These tier-one entities maintain competitive moats through extensive patent portfolios, vertically integrated powder synthesis, and long-term supply agreements with leading multinational electronics manufacturers and automotive tier-one suppliers.
Executive summary of key findings in the Ferroelectric Materials Market analysis
Our proprietary research establishes that the Ferroelectric Materials Market is poised for stellar expansion, surging from 3.85 Billion in 2026 to reach 6.93 Billion by 2033. Registering a robust CAGR of 8.76%, this growth trajectory is heavily anchored in automotive electrification, advanced telecommunications infrastructure upgrades, and next-generation ceramic capacitor manufacturing.
Market forecast and long-term trajectory from 2027 to 2033
Driven by compounding adoption across healthcare transducers and electric vehicle powertrain sensors, the market will expand steadily through 2033. Our models project that cumulative sector revenues will scale from 3.85 Billion in 2026 to 6.93 Billion by the end of the forecast period, representing a sustained compound annual growth rate of 8.76%.
Comprehensive segmentation breakdown of the Ferroelectric Materials Market
The market is meticulously segmented by type into Barium Titanate, Lead Zirconate Titanate, Lead Titanate, and other advanced formulations including Sodium Potassium Niobate and Polyvinylidene Fluoride. Application parameters divide into Ceramic Capacitors, PTC Thermistors, and specialized transducers, serving vital end-use verticals spanning electronics, telecommunications, healthcare diagnostics, and automotive systems.
Geographic distribution and regional performance in the Ferroelectric Materials Market
Asia-Pacific commands the lion's share of market consumption, anchored by massive electronics manufacturing hubs in Japan, South Korea, and China. North America and Europe follow closely, driven by stringent technological innovation in healthcare imaging equipment, aerospace actuators, and automotive sensor deployment. Regional growth closely mirrors local semiconductor fab density and passive component production capacities.
In-depth regional review of manufacturing hubs and consumption centers
Asian markets benefit from localized processing capabilities for raw precursors, championed by regional specialists like Sakai Chemical Industry Co Ltd and Shandong Sinocera Functional Material Co. Meanwhile, European and North American facilities focus heavily on high-margin, specialized medical-grade PZT ceramics and custom piezoelectric assemblies engineered by firms like CeramTec and CTS Corporation.
Company profiles and strategic positioning of leading industry players
Industry leaders employ distinct strategies to capture market share. Murata Manufacturing Co. Ltd. and TDK Corporation leverage immense production scale for multilayer ceramic capacitors. Concurrently, high-purity specialists such as Morgan Advanced Materials and Ferro Corporation focus on bespoke powder formulations and advanced ceramic components for demanding industrial actuators.
Porter's Five Forces analysis of competitive intensity
Bargaining power of raw material suppliers is moderate to high due to the strict purity requirements of Barium Titanate precursors. Competitive rivalry is intense among established market giants, while threat of substitutes remains constrained by the unmatched electromechanical coupling efficiency unique to ferroelectric ceramics.
SWOT analysis highlighting strategic strengths and market threats
Strengths lie in exceptional dielectric properties and high thermal stability. Weaknesses involve complex, energy-intensive synthesis processes. Opportunities abound in lead-free transducer development and 5G filter components, while threats center on raw material price volatility and rigorous environmental regulations targeting hazardous heavy metals.
Value chain analysis from raw material synthesis to end-user deployment
The value chain initiates with the chemical refinement of high-purity mineral precursors like titanium dioxide and barium carbonate. Midstream processors compound these into specialized powders before shaping and sintering. Downstream entities integrate these functional ceramics into finished capacitors and sensors destined for automotive and telecommunications giants.
Investment insights and high-potential focus areas for stakeholders
Strategic capital should target emerging lead-free material formulations, specifically Sodium Potassium Niobate and high-performance PVDF polymers. Investors are advised to partner with mid-stream innovators capable of scaling eco-friendly synthesis routes to circumvent tightening global environmental regulations without sacrificing electromechanical performance metrics.
Conclusion and core takeaways from the market evaluation
In summary, the Ferroelectric Materials Market offers compelling growth prospects, projected to reach 6.93 Billion by 2033 at an 8.76% CAGR. Navigating this landscape successfully demands proactive adaptation to environmental mandates and strategic investments in advanced lead-free material innovations.
Research methodology detailing baseline estimation and data triangulation
Our baseline estimates are rigorously triangulated by combining comprehensive import-export trade registry data, primary executive-level stakeholder interviews across tier-one manufacturers, and macroeconomic industrial output indicators. This multi-layered approach ensures high fidelity in sizing niche material segments and forecasting regional consumption patterns.
Scope of the report, coverage parameters, and operational limitations
This comprehensive report evaluates the global Ferroelectric Materials Market across specified material types, applications, and end-use sectors from 2026 through 2033. Limitations include potential unforeseen geopolitical shifts affecting rare earth and precursor mineral supply chains, which are continuously monitored through our proprietary tracking models.
Recent developments, corporate partnerships, and product launches
Recent strategic moves feature aggressive R&D investments by industry leaders into eco-friendly ceramic formulations to comply with evolving international environmental standards. Companies like TRS Technologies Inc. and Smart Material Corporation have announced collaborative ventures aimed at advancing high-temperature piezoelectric composites for next-generation aerospace and medical imaging applications.